Budget Planning
How Silicon Valley Facility Managers Can Slash 2026 Operating Costs by 23%
January 12, 2026
By the first week of March, you have approximately ten weeks of real operational data from 2026. That data tells a story about what your annual facility budget got right, what it missed, and where the remaining three quarters need adjustment.
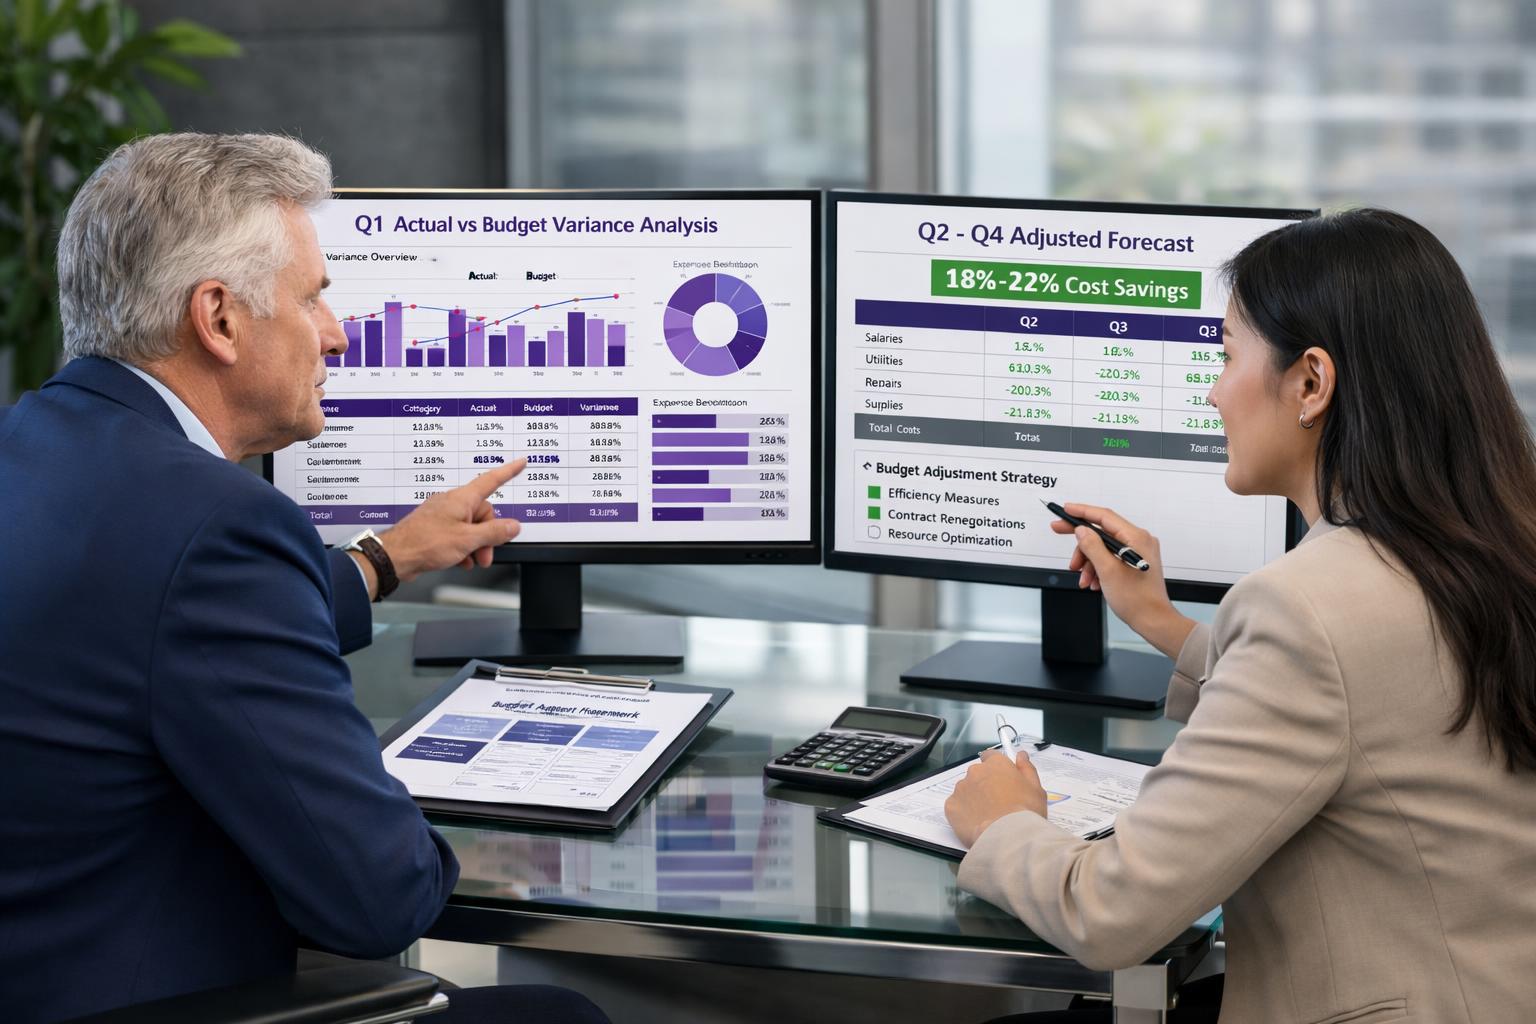
Facility managers who treat their annual budget as a fixed document spend more money and get worse results than those who use Q1 actuals to recalibrate. The difference is significant. Properties that conduct quarterly budget reviews and mid-year adjustments consistently report 18-22% better cost performance than those running static annual budgets.
Here is how to turn your Q1 data into a precise roadmap for the rest of 2026.
Before adjusting anything, you need a clear picture of where Q1 landed relative to plan. Pull your actual expenditures across every facility budget line item and compare them against your January projections.
Start with the big three categories that drive 70-80% of facility spending: labor and staffing costs, supplies and materials, and contracted services. For each category, calculate the variance, both in dollars and percentage, between what you budgeted and what you actually spent.
Variances under 5% in any category suggest your projections were solid. Variances between 5-15% indicate areas that need recalibration but not restructuring. Variances exceeding 15% signal either a fundamental change in operating conditions or a projection methodology that needs rethinking.
Pay special attention to utility costs. Silicon Valley's energy pricing has shifted noticeably, and Q1 utility actuals often reveal whether your rate assumptions for the year still hold. If your electricity costs ran 10% over budget in Q1, projecting that same overage across three more quarters means a significant annual miss unless you adjust now.
Facility costs in the Bay Area follow predictable seasonal patterns that your Q2-Q4 budget should reflect. Failing to account for these patterns is one of the most common budgeting errors.
Q2 (April-June) typically brings the lowest utility costs of the year. Mild spring temperatures mean reduced HVAC load, which translates to electricity savings of 12-20% compared to Q1. However, Q2 also brings increased landscaping expenses as irrigation systems activate and growing season maintenance ramps up.
Q3 (July-September) is historically the highest-cost quarter for Silicon Valley facilities. Summer heat drives HVAC costs up 20-35% over spring levels. Fire season preparation requires additional exterior maintenance and vegetation management. Tenant activity often peaks as companies push to meet annual goals, which increases wear on common areas and restrooms.
Q4 (October-December) brings moderate utility costs but spikes in holiday-related cleaning, end-of-year project completions, and budget-flush spending where deferred maintenance finally gets approved. Many Silicon Valley companies also conduct office reorganizations and build-outs in Q4, which increases facility management workload.
Build these seasonal patterns into your quarterly allocations rather than dividing your annual budget by four equal parts.
Every facility has budget leaks, recurring overspends that look small monthly but compound into significant annual waste. Q1 data gives you enough runway to identify and plug these leaks before they drain the full-year budget.
The most common budget leaks in Silicon Valley commercial properties include overtime labor driven by reactive maintenance rather than planned work, supply overspending caused by emergency purchasing at retail prices instead of contracted wholesale rates, and energy waste from HVAC scheduling that does not align with actual occupancy patterns.
Review your maintenance work order data from Q1. Calculate the ratio of planned work orders to emergency work orders. If emergency work exceeds 30% of total work orders, your preventive maintenance program needs strengthening, and your budget needs to shift dollars from reactive line items to proactive ones.
Check your supply purchasing records for one-off orders placed outside your primary vendor contracts. These off-contract purchases typically cost 25-40% more than contracted pricing. If you see a pattern, it usually means your supply par levels are set too low or your ordering frequency does not match consumption rates.
With your Q1 actuals analyzed, seasonal factors mapped, and budget leaks identified, you can build an adjusted forecast that reflects reality rather than January optimism.
Start by annualizing your Q1 actuals with seasonal adjustments. Take each budget category's Q1 actual spend, multiply by four for a raw annualization, then apply the seasonal adjustment factors for Q2-Q4 that reflect Silicon Valley's cost patterns.
Next, layer in known changes. If you have contracts renewing in Q2 or Q3, use the actual renewal rates rather than estimated figures. If you are adding or losing tenants, adjust cleaning and maintenance scopes accordingly. If capital projects are scheduled, confirm their timing and budget impact.
Then apply your budget leak corrections. For every leak you identified, estimate the quarterly savings from plugging it and reduce the corresponding budget line. Be conservative, assume you will capture 60-70% of the identified savings rather than 100%.
Finally, build a contingency reserve of 5-8% across all categories. This is not padding, it is disciplined risk management that prevents a single unexpected expense from derailing your entire budget.
The best budget adjustment in the world fails if it does not get buy-in from property owners, asset managers, and tenant representatives. How you present your mid-year adjustment matters as much as the numbers themselves.
Lead with the story the data tells. Open with your Q1 performance summary, where you came in under budget, where you exceeded projections, and the total variance. This establishes credibility before you ask for any changes.
Present adjustments as investment decisions, not cost increases. Frame additional spending in terms of prevented costs and asset protection. A $5,000 increase in preventive maintenance spending is not a budget overrun, it is a decision that prevents $15,000-$20,000 in emergency repairs.
Provide three scenarios: optimistic, expected, and conservative. Give stakeholders context for the range of possible outcomes and let them see how your recommended budget positions the property for each scenario.
Include specific metrics you will track quarterly to measure whether the adjusted budget is performing. Stakeholders gain confidence when they see accountability built into the plan.
Monthly budget tracking should take no more than two hours once your system is established. The key is setting up your tracking framework now so Q2 monitoring happens automatically.
Create a simple variance dashboard that compares monthly actuals to your adjusted budget in real time. Flag any line item that exceeds its monthly allocation by more than 10% for immediate review. Track your planned-versus-reactive maintenance ratio monthly as a leading indicator of future cost performance.
Set calendar reminders for the first week of each month to pull data and update your dashboard. Schedule a quarterly deep-dive review for the first week of April, July, and October to repeat this same analysis process.
Your Q1 data is a gift, it is the most accurate predictor you have for how the rest of 2026 will unfold. Facility managers who use that data to recalibrate their budgets outperform those who wait until year-end to discover their projections were wrong.
The window for mid-year adjustment is right now. Pull your Q1 actuals this week, run the analysis, and build your adjusted forecast before March ends. You will enter Q2 with a budget that reflects operational reality rather than annual guesswork, and that precision compounds into significant savings by December.
MAFM provides data-driven facility management that optimizes every dollar of your operating budget, including quarterly performance analysis and budget optimization strategies.
Schedule your consultation: Contact MAFM.PRO
MAFM offers comprehensive facility management solutions tailored to your business needs.
Get in Touch